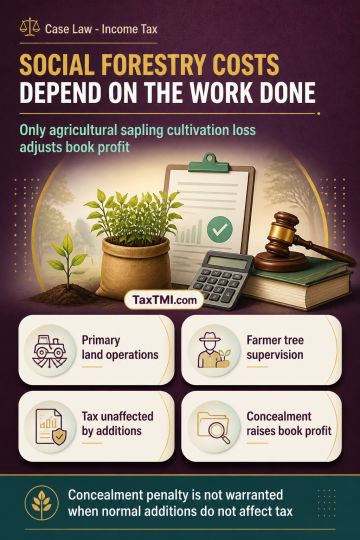
Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
For AY 2019-20, the option for deemed application of charitable trust income had to be exercised before expiry of the time allowed for filing the return. Form No. 9A filed before the extended return-filing due date met that requirement. The later requirement to furnish Form No. 9A at least two months before the return-filing due date applies prospectively from AY 2023-24. Statutory accumulation or setting apart of income within the permissible fifteen per cent limit is separate from deemed application and does not depend on Form No. 9A, unless the accumulation exceeds that limit.
For AY 2019-20, the option for deemed application of charitable trust income had to be exercised before expiry of the time allowed for filing the return. Form No. 9A filed before the extended return-filing due date met that requirement. The later requirement to furnish Form No. 9A at least two months before the return-filing due date applies prospectively from AY 2023-24. Statutory accumulation or setting apart of income within the permissible fifteen per cent limit is separate from deemed application and does not depend on Form No. 9A, unless the accumulation exceeds that limit.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI