Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
Software sub-licensing was treated as provision of services...
Transfer-pricing tolerance for software sub-licensing falls within the services range, eliminating the adjustment and requiring TDS-credit verification.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
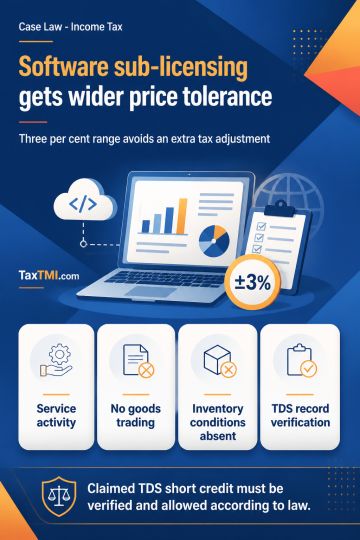
Software sub-licensing was treated as provision of services rather than wholesale trading for transfer-pricing tolerance purposes. With four comparable companies in the final dataset, Rule 10CA(7) applied, and the one per cent variation reserved for wholesale trading did not apply because the activity neither involved goods trading nor met inventory conditions. The difference between the arm's length price and transaction price fell within the applicable three per cent range, so the transfer-pricing adjustment was deleted and benchmarking and comparable challenges required no decision. Claimed TDS short credit requires record verification and allowance in accordance with law.
Software sub-licensing was treated as provision of services rather than wholesale trading for transfer-pricing tolerance purposes. With four comparable companies in the final dataset, Rule 10CA(7) applied, and the one per cent variation reserved for wholesale trading did not apply because the activity neither involved goods trading nor met inventory conditions. The difference between the arm's length price and transaction price fell within the applicable three per cent range, so the transfer-pricing adjustment was deleted and benchmarking and comparable challenges required no decision. Claimed TDS short credit requires record verification and allowance in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI