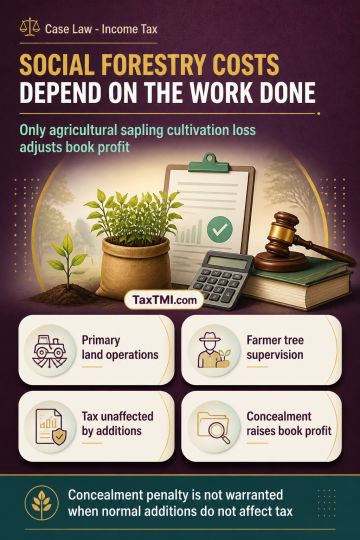
Social forestry expenditure requires activity-based classification, limiting book-profit adjustments and preserving penalty relief where normal additi...
For insolvency appeals, statutory limitation remains strict and...
E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
For insolvency appeals, statutory limitation remains strict and the Tribunal cannot condone delay beyond the prescribed outer period. Limitation does not run, however, while the filing forum is unavailable or incapable of receiving filings. A bona fide attempt to e-file within time that fails solely because the Tribunal's OTP delivery system malfunctioned warrants exclusion of the non-functional period under actus curiae neminem gravabit, with the initial attempt treated as the presentation date. The time-bar dismissal was set aside and the appeal, with its delay-condonation application, was restored for reconsideration, subject to sufficient cause.
For insolvency appeals, statutory limitation remains strict and the Tribunal cannot condone delay beyond the prescribed outer period. Limitation does not run, however, while the filing forum is unavailable or incapable of receiving filings. A bona fide attempt to e-file within time that fails solely because the Tribunal's OTP delivery system malfunctioned warrants exclusion of the non-functional period under actus curiae neminem gravabit, with the initial attempt treated as the presentation date. The time-bar dismissal was set aside and the appeal, with its delay-condonation application, was restored for reconsideration, subject to sufficient cause.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI