Concurrent anticipatory-bail jurisdiction permits applications before either forum, while secured evidence may negate custodial interrogation in GST e...
Transfer Pricing Officer jurisdiction is transaction-specific, excluding permanent establishment determinations and requiring independent assessment o...
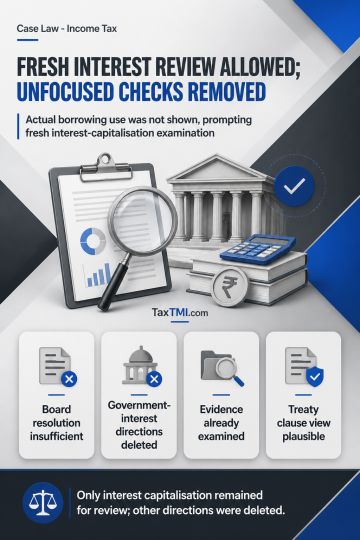
Section 263 revision was sustained for fresh examination of interest capitalisation because the actual use of external commercial borrowings for working capital was not demonstrated and the Assessing Officer had made no enquiry; a board resolution stating the borrowing purpose was insufficient. Revision could not, however, reopen matters already examined or direct unfocused verification. Directions concerning tax deduction on interest paid to Government authorities were deleted as they amounted to a fishing or roving enquiry without an identified assessment error. Re-examination of miscellaneous expenditure and service-provider charges was also deleted because the Assessing Officer had examined the evidence and adopted a plausible view, including on the treaty's make available clause.
Section 263 revision was sustained for fresh examination of interest capitalisation because the actual use of external commercial borrowings for working capital was not demonstrated and the Assessing Officer had made no enquiry; a board resolution stating the borrowing purpose was insufficient. Revision could not, however, reopen matters already examined or direct unfocused verification. Directions concerning tax deduction on interest paid to Government authorities were deleted as they amounted to a fishing or roving enquiry without an identified assessment error. Re-examination of miscellaneous expenditure and service-provider charges was also deleted because the Assessing Officer had examined the evidence and adopted a plausible view, including on the treaty's make available clause.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI