Extension of the ninety-day period for considering a compromise...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids procedural rejection.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
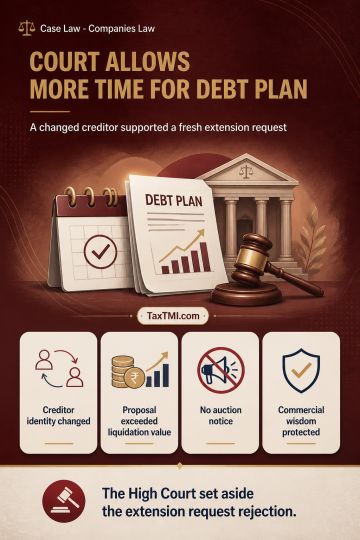
Extension of the ninety-day period for considering a compromise or arrangement in liquidation may be granted where circumstances materially change after an earlier rejection. Assignment of the debt changed the identity of the sole financial creditor and the relevant commercial decision-maker, so a fresh extension request was procedural rather than a collateral challenge to the earlier merits decision. Support from the sole financial creditor and a proposal exceeding liquidation value advanced value maximisation. In the absence of an auction notice or resulting prejudice, the NCLT could not replace the financial creditor's commercial wisdom with its own view. The High Court set aside the rejection of the extension request.
Extension of the ninety-day period for considering a compromise or arrangement in liquidation may be granted where circumstances materially change after an earlier rejection. Assignment of the debt changed the identity of the sole financial creditor and the relevant commercial decision-maker, so a fresh extension request was procedural rather than a collateral challenge to the earlier merits decision. Support from the sole financial creditor and a proposal exceeding liquidation value advanced value maximisation. In the absence of an auction notice or resulting prejudice, the NCLT could not replace the financial creditor's commercial wisdom with its own view. The High Court set aside the rejection of the extension request.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI