Handicraft job work receives concessional GST only for registered principals and predominantly handmade goods; commercial resin articles remain taxabl...
Reassessment disclosure requirements permit stated reasons without revealing information sources, but prior-taxation claims require full examination b...
Independent assessment discretion and corroborated electronic evidence determine validity of on-money additions and undisclosed-consideration assessme...
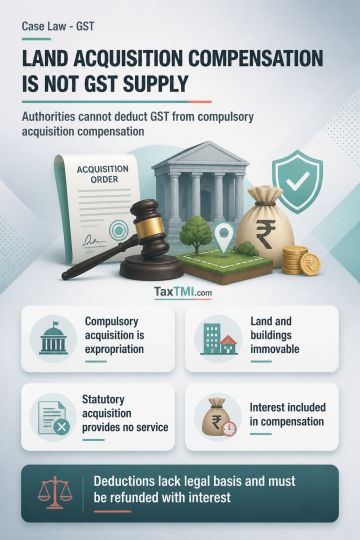
Compulsory acquisition of land and attached structures under eminent-domain powers is an expropriation, not a supply of goods or services for GST purposes. Land and buildings are immovable property and cannot be treated as goods, while a landowner does not provide any service through statutory acquisition. GST deducted from acquisition compensation therefore lacks statutory basis, is beyond the acquiring authority's power, and must be refunded with interest. Interest awarded on compensation under the Land Acquisition Act to account for the period until payment forms part of compensation and is not subject to tax deduction at source.
Compulsory acquisition of land and attached structures under eminent-domain powers is an expropriation, not a supply of goods or services for GST purposes. Land and buildings are immovable property and cannot be treated as goods, while a landowner does not provide any service through statutory acquisition. GST deducted from acquisition compensation therefore lacks statutory basis, is beyond the acquiring authority's power, and must be refunded with interest. Interest awarded on compensation under the Land Acquisition Act to account for the period until payment forms part of compensation and is not subject to tax deduction at source.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935