Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
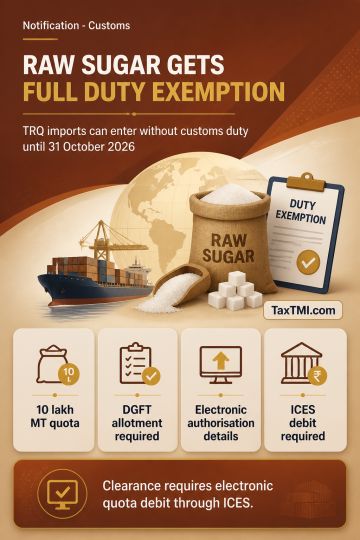
Raw sugar under tariff heading 1701 is exempt from the whole of customs duty under the First Schedule to the Customs Tariff Act when imported within a Tariff Rate Quota of 10 lakh MT. The exemption applies immediately until 31 October 2026. Importers must receive TRQ allotment from DGFT under the applicable Handbook of Procedures, and the electronic authorisation must identify the importer, IEC, notification, tariff heading, quantity and validity. Customs clearance is permitted only through electronic debit of the authorised quota in ICES.
Raw sugar under tariff heading 1701 is exempt from the whole of customs duty under the First Schedule to the Customs Tariff Act when imported within a Tariff Rate Quota of 10 lakh MT. The exemption applies immediately until 31 October 2026. Importers must receive TRQ allotment from DGFT under the applicable Handbook of Procedures, and the electronic authorisation must identify the importer, IEC, notification, tariff heading, quantity and validity. Customs clearance is permitted only through electronic debit of the authorised quota in ICES.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897