GST refund limitation: COVID-19 exclusion preserves timely advance-tax refunds, while deficiency-memo corrections relate back to the original applicat...
Presumptive taxation of oilfield services applies to receipts inextricably connected with mineral-oil operations, while qualifying offshore supplies r...
Government financing for educational exemptions includes UGC grants and land-related notional interest, eliminating penalties tied to deleted addition...
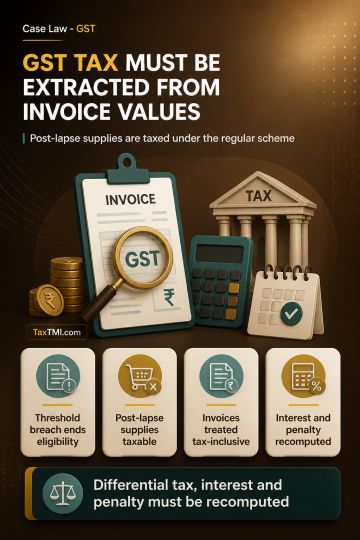
Composition-scheme eligibility lapses automatically on the day aggregate turnover exceeds the prescribed threshold. Supplies made thereafter are taxable under the regular scheme, with adjustment for composition tax paid on post-lapse turnover; the cessation of composition eligibility was sustained. For post-lapse supplies where tax was not separately collected, invoice values must be treated as tax-inclusive because a composition taxpayer cannot collect tax separately and no additional collection was alleged. Rule 35 requires extraction of the tax component from the cum-tax value. Differential tax, and consequential interest and penalty, must therefore be recomputed on that basis.
Composition-scheme eligibility lapses automatically on the day aggregate turnover exceeds the prescribed threshold. Supplies made thereafter are taxable under the regular scheme, with adjustment for composition tax paid on post-lapse turnover; the cessation of composition eligibility was sustained. For post-lapse supplies where tax was not separately collected, invoice values must be treated as tax-inclusive because a composition taxpayer cannot collect tax separately and no additional collection was alleged. Rule 35 requires extraction of the tax component from the cum-tax value. Differential tax, and consequential interest and penalty, must therefore be recomputed on that basis.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI