Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
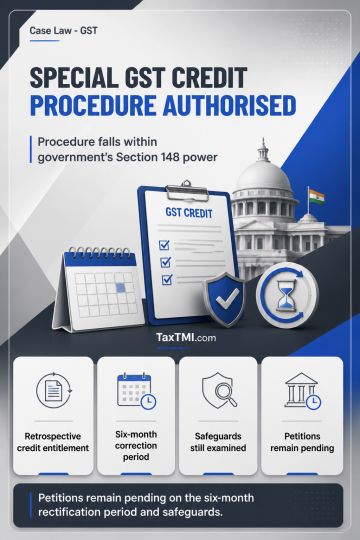
Section 148 permits the Government, on the Council's recommendations and subject to conditions and safeguards, to notify classes of registered persons and special procedures for registration, returns, tax payment and administration. Notification No. 22/2024-Central Tax, prescribing a procedure to implement retrospective input tax credit entitlement under Section 16(5), therefore falls within that power. The validity of the stipulated six-month period for rectification, particularly whether it contains adequate safeguards despite no extension mechanism for extraordinary circumstances, remains under consideration. The writ petitions were kept pending on that limited issue.
Section 148 permits the Government, on the Council's recommendations and subject to conditions and safeguards, to notify classes of registered persons and special procedures for registration, returns, tax payment and administration. Notification No. 22/2024-Central Tax, prescribing a procedure to implement retrospective input tax credit entitlement under Section 16(5), therefore falls within that power. The validity of the stipulated six-month period for rectification, particularly whether it contains adequate safeguards despite no extension mechanism for extraordinary circumstances, remains under consideration. The writ petitions were kept pending on that limited issue.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935