Concessional penalty for search-disclosed unreconciled jewellery applies where substantive disclosure conditions are met despite omission from origina...
Alternative statutory remedy and unexplained delay barred writ review of customs confiscation adjudication, leaving merits for appellate consideration...
Page of 4935
Press 'Enter' after typing page number.
2201 to 2220 of 98695 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
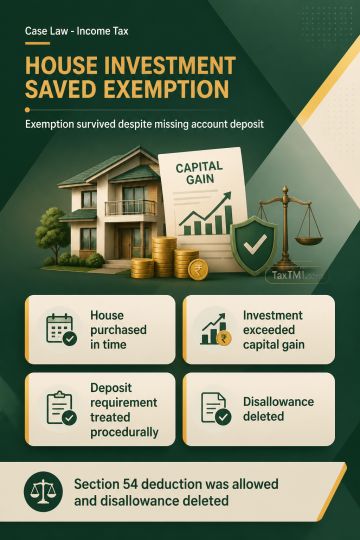
Section 54 capital-gains exemption remains available where capital gains are invested in a new residential house within the prescribed period, even if the unutilised amount was not deposited in the Capital Gains Account Scheme before the return-filing due date. Treating section 54 as a beneficial provision, the Tribunal regarded the deposit requirement as procedural where the substantive investment condition was met. The taxpayer's share in the jointly acquired property exceeded the capital gain and the purchase occurred before the extended return-filing due date. Accordingly, the section 54 deduction was allowed and the disallowance was deleted.
Section 54 capital-gains exemption remains available where capital gains are invested in a new residential house within the prescribed period, even if the unutilised amount was not deposited in the Capital Gains Account Scheme before the return-filing due date. Treating section 54 as a beneficial provision, the Tribunal regarded the deposit requirement as procedural where the substantive investment condition was met. The taxpayer's share in the jointly acquired property exceeded the capital gain and the purchase occurred before the extended return-filing due date. Accordingly, the section 54 deduction was allowed and the disallowance was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935