Concessional corporate tax option under section 115BAA survives procedural documentary lapses when statutory compliance and earlier exercise are estab...
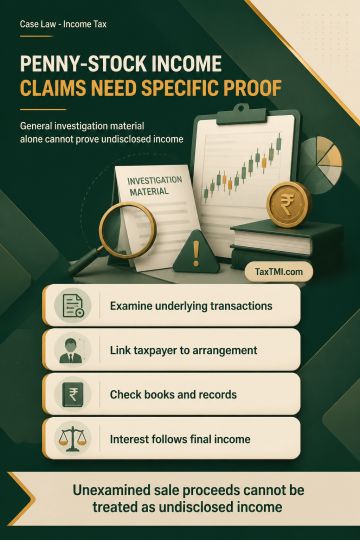
Penny-stock additions require transaction-specific evidence; general investigation material alone cannot establish undisclosed income or accommodation...
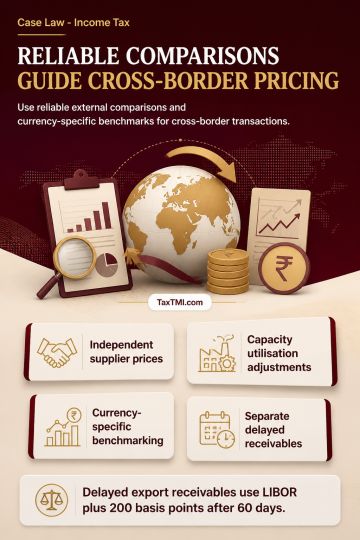
Transfer pricing comparability prioritises reliable external CUPs and foreign-currency LIBOR benchmarks for exports, borrowings and delayed receivable...
Section 153C satisfaction and seized electronic records sustained unexplained-investment addition, subject to proportionate ownership-share verificati...
Contributions to an electricity board for augmenting a...
Electricity network contributions remain revenue expenditure where ownership and maintenance stay with the electricity board, supporting business profitability.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Contributions to an electricity board for augmenting a transmission network may constitute revenue expenditure under Section 37(1) where the board retains ownership, maintenance responsibility and the right to use the service line for other consumers. No tangible asset, ownership right or enduring capital asset arises for the contributor in those circumstances. The expenditure is incurred to improve the profitability of the existing business apparatus and does not render an assessment order erroneous or prejudicial to revenue merely because it was allowed as revenue expenditure.
Contributions to an electricity board for augmenting a transmission network may constitute revenue expenditure under Section 37(1) where the board retains ownership, maintenance responsibility and the right to use the service line for other consumers. No tangible asset, ownership right or enduring capital asset arises for the contributor in those circumstances. The expenditure is incurred to improve the profitability of the existing business apparatus and does not render an assessment order erroneous or prejudicial to revenue merely because it was allowed as revenue expenditure.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929