Pure-agent exclusion fails where hotel booking facilitators receive third-party services themselves, making entire customer consideration taxable as r...
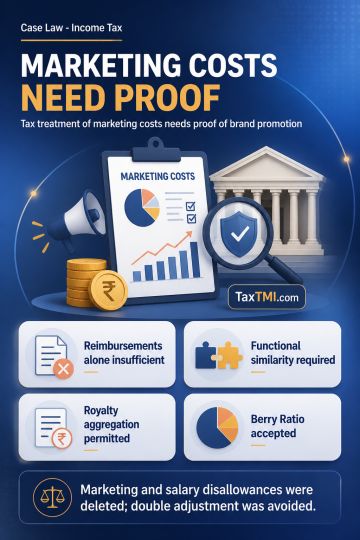
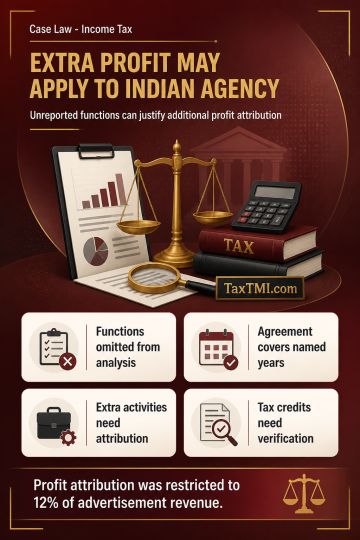
Transfer pricing requires evidence for AMP transactions, functionally reliable comparables, and appropriate aggregation or Berry Ratio benchmarking me...
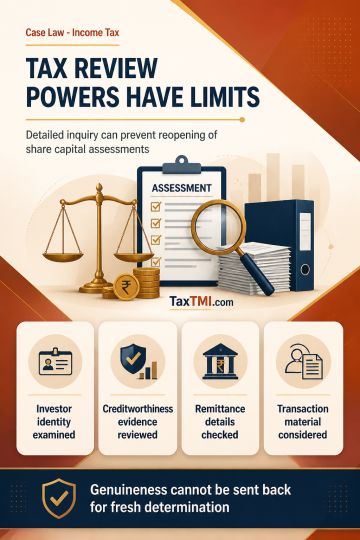
Revisionary jurisdiction cannot reopen share capital assessments where adequate inquiry supports a permissible view and no independent error is establ...
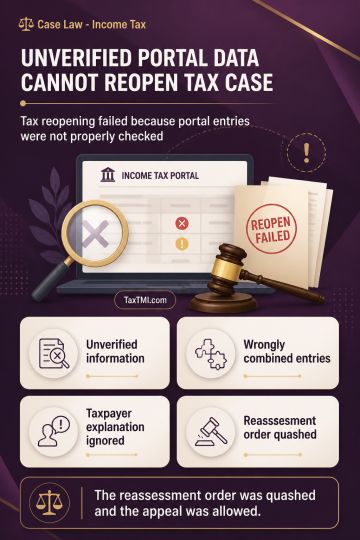
Reassessment jurisdiction fails where unverified portal information is aggregated without examining the taxpayer's explanation or relevance of entries...
Statutory sanction for delayed reassessment requires approval from the prescribed authority; approval by an inferior authority invalidates jurisdictio...
Transfer pricing margin adjustments require matching treatment of non-operating income and related costs, with comparability issues reconsidered on ev...
Preliminary-expense amortisation and MAT exempt-income adjustments prevailed, while trademark costs and managerial remuneration require fresh verifica...
Export valuation requires contemporaneous evidence; unrelated invoices cannot prove overvaluation, and dual penalties on firm and partner are impermis...
Page of 4897
Press 'Enter' after typing page number.
2061 to 2080 of 97923 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Nature-dependent electricity contracts receive new Ind AS accounting, hedge designation, transition and financial-statement disclosure requirements from annual periods beginning April 2026.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Companies (Indian Accounting Standards) Amendment Rules, 2026 amend Ind AS 101, 107, 109, 110 and 7, taking effect on publication in the Official Gazette. The amendments establish accounting, hedge-accounting, transition and disclosure requirements for contracts referencing nature-dependent electricity, including assessment of expected usage, net-purchaser status, financial-statement disclosures and optional fair-value-through-profit-or-loss designation at initial application. They also revise financial-instrument classification and measurement guidance, including contingent cash flows, basic lending arrangements, non-recourse features, electronic-payment derecognition and related disclosures. Most specified amendments apply to annual reporting periods beginning on or after 1 April 2026, with retrospective application subject to prescribed transition reliefs and opening-equity adjustments where comparative periods are not restated.
Companies (Indian Accounting Standards) Amendment Rules, 2026 amend Ind AS 101, 107, 109, 110 and 7, taking effect on publication in the Official Gazette. The amendments establish accounting, hedge-accounting, transition and disclosure requirements for contracts referencing nature-dependent electricity, including assessment of expected usage, net-purchaser status, financial-statement disclosures and optional fair-value-through-profit-or-loss designation at initial application. They also revise financial-instrument classification and measurement guidance, including contingent cash flows, basic lending arrangements, non-recourse features, electronic-payment derecognition and related disclosures. Most specified amendments apply to annual reporting periods beginning on or after 1 April 2026, with retrospective application subject to prescribed transition reliefs and opening-equity adjustments where comparative periods are not restated.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897